Everyone in the exhibition business is reading the Fortress Investment Group sale process for Curzon Cinemas completely backward.
The financial press loves a tidy narrative. Private equity buys an asset, hits a macro headwind, and dumps the keys on the table before the lease obligations drown the balance sheet. When news broke that Fortress was quietly testing buyer appetite for the UK arthouse circuit and its integrated distribution arm, the armchair analysts immediately labeled it a distress exit. They pointed to post-pandemic box office recovery lags, the lingering scar tissue of the Hollywood strikes, and rising UK commercial property rates. They assumed Fortress wanted out because cinemas are a dying business. Expanding on this topic, you can find more in: The Night the Machines Went Public.
They missed the entire plot.
Fortress didn't step in to rescue Curzon out of charitable love for independent film, and they aren't exploring a sale because the model is broken. They are testing the market because the heavy lifting of vertical integration is finally done, and the asset is now worth far more to a strategic media buyer than it ever could be sitting inside a distressed-debt fund's portfolio. Observers at Harvard Business Review have shared their thoughts on this matter.
The Myth of the Failing Arthouse Model
To understand why the "distress sale" consensus is lazy, you have to look at how traditional multiplexes actually make money versus how Curzon operates.
Legacy exhibitors like Cineworld or AMC are essentially real estate and popcorn arbitrage plays. They lease massive, high-overhead concrete boxes in retail parks, rely on Hollywood studios to spend $100 million marketing a superhero tentpole, and pray they make enough margin on carbonated sugar water to cover the debt service. When studio output dries up, their entire business model collapses.
Curzon plays a fundamentally different game.
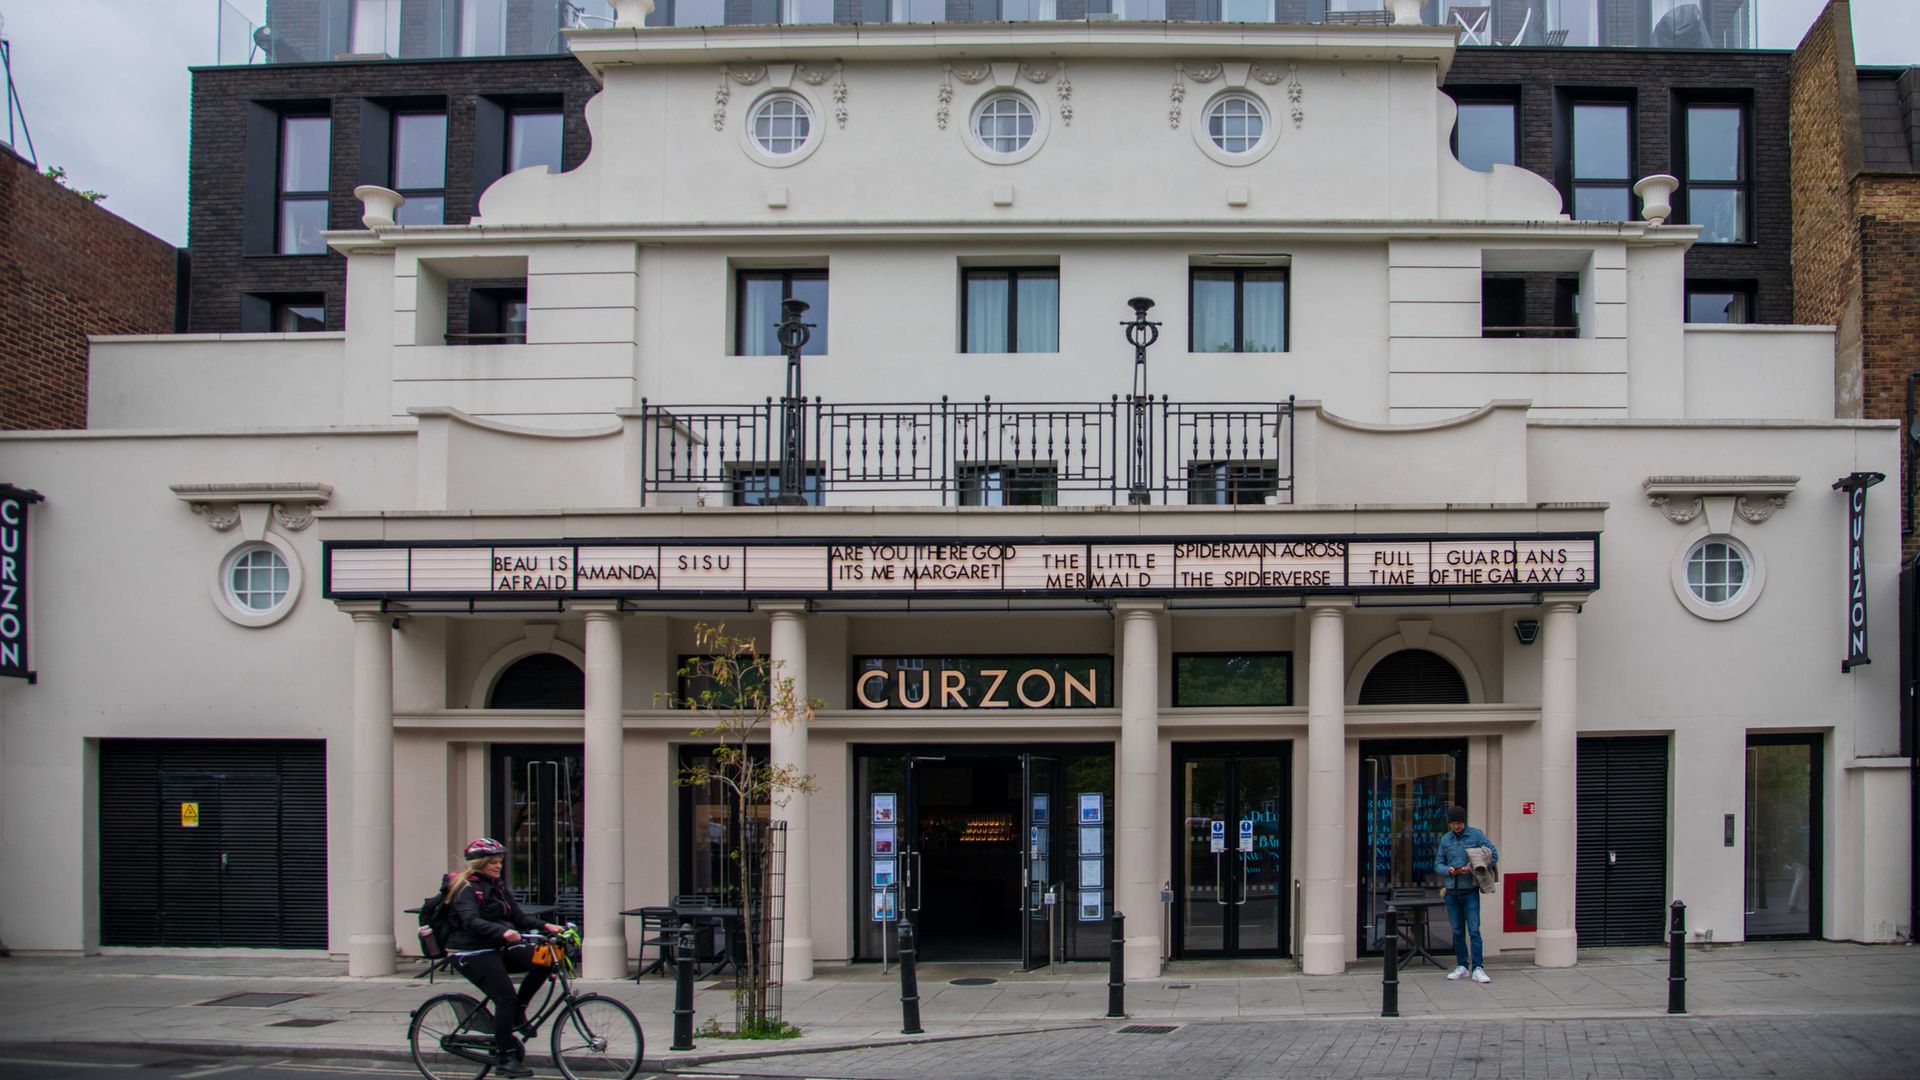
When Fortress acquired Curzon in late 2019—just months before lockdowns shuttered every theater on earth—they weren't buying a chain of movie theaters. They were buying an end-to-end content ecosystem. Curzon Artificial Eye doesn't just put butts in velvet seats in Soho or Mayfair; it acquires distribution rights, runs a direct-to-consumer streaming platform (Curzon Home Cinema), and controls the theatrical release window in the UK and Ireland.
I have watched private equity firms burn tens of millions of dollars trying to roll up regional cinema chains, assuming that scale alone fixes unit economics. It never does. Buying thirty struggling screens doesn't give you pricing power against Disney; it just multiplies your rent liabilities. Fortress avoided that trap by doubling down on Curzon’s structural moat: curated scarcity and vertical control.
What the Balance Sheet Actually Says
Let’s strip away the emotional attachment people have to cinema and look at the mechanics of a private equity hold period.
- The Entry Point: Fortress took control when Curzon needed capital to survive and expand, securing the asset at a valuation depressed by structural retail anxiety.
- The Capital Expenditure Cycle: Over the past few years, Fortress funded site expansions—opening flagship venues like Camden and Kingston—while absorbing the brutal cash burn of the 2020–2021 closures and the 2023 labor stoppages.
- The Inflection Point: In private equity, you do not hold an asset through the messy, capital-intensive construction phase only to sell it at the exact moment the slate normalizes and cap-ex tapers off—unless you believe you can command a strategic premium.
If Fortress were panicking, you would see fire-sale restructuring, aggressive site closures, and a quiet handover to creditors—the exact playbook that played out during Cineworld's Chapter 11 restructuring. Instead, Fortress is running a structured market-testing process with investment bankers to gauge strategic interest. You don't screen-test buyers for a burning building. You screen-test buyers when the renovations are finished and the neighborhood just got rezoned.
Why Strategic Buyers Are Circles Around a "Dying" Industry
If cinemas are supposedly obsolete, why are investment bankers even bothering to pick up the phone? Because the buyers looking at Curzon aren't traditional theater operators.
Imagine a scenario where a global streaming giant—think Apple, Amazon, or MUBI—wants to solve its biggest prestige problem. Digital platforms have infinite shelf space, yet they suffer from severe discovery fatigue and a lack of cultural legitimacy. When Amazon bought MGM or when Netflix bought the Paris Theater in New York and the Egyptian Theatre in Los Angeles, they weren't trying to corner the market on concession sales. They were buying cultural tastemaking infrastructure and awards-season credibility.
For a streamer or a major European studio like StudioCanal or Pathé, owning Curzon solves three massive operational headaches overnight:
- Guaranteed Theatrical Windows: Major festival winners and auteur directors still demand a real theatrical run before hitting streaming. Owning the premier UK arthouse circuit guarantees screen space in London, the most important media market in Europe.
- Built-In Marketing Loops: A sold-out Q&A at Curzon Soho generates press coverage across The Guardian, Sight and Sound, and Empire that you simply cannot buy with programmatic digital ads. That theatrical halo directly drives transactional video-on-demand (TVOD) and subscription numbers on the backend.
- First-Party Data on Affluent Audiences: Multiplexes barely know who walks through their doors. Curzon’s membership program tracks the exact viewing habits, spending power, and taste profiles of the UK’s highest-earning, most culturally engaged demographic.
The financial press keeps asking whether Curzon’s box office receipts have returned to 2019 levels. That is the wrong question entirely. Box office ticket splits are the loss leader in this ecosystem. The real value is the customer acquisition cost (CAC) subsidy that the physical cinemas provide for the distribution and home-entertainment divisions.
The Structural Trap Fortress Wants to Escape
Admitting that Curzon is a trophy strategic asset does not mean Fortress is executing a flawless victory lap. To be completely transparent about the mechanics here, Fortress has a very real, pragmatic reason to exit now—and it has nothing to do with the death of cinema.
Fortress is fundamentally a credit and special-situations powerhouse. Their DNA is built around complex debt restructuring, distressed real estate, and asset-backed lending—not long-term brand stewardship in the European cultural sector.
Managing a boutique cinema chain requires tolerating messy, low-margin retail variables that give credit investors hives:
- UK Commercial Real Estate Friction: Upward-only rent reviews and punitive business rates in central London eat directly into operating margins, regardless of how well a film performs.
- Labor and Hospitality Inflation: Curzon’s model relies on high-touch hospitality—bars, lounges, curated events—which leaves the business heavily exposed to UK minimum wage increases and hospitality supply chain inflation.
- Working Capital Volatility: Independent film distribution requires putting up minimum guarantees (MGs) at markets like Cannes and Berlin months or years before a single ticket is sold.
For a fund like Fortress, continuing to hold Curzon means dedicating senior operational bandwidth to managing London landlords and hospitality margins just to eke out incremental EBITDA growth. They took the asset from distress to stabilization. Passing the baton to a strategic media company—one that measures return on investment in subscriber retention, library value, and prestige rather than pure real estate yield—is the most logical capital allocation move on the board.
What Everyone Gets Wrong About Cinema Valuations
When analysts try to value a company like Curzon, they instinctively reach for standard exhibition multiples—usually a depressed multiple of trailing EBITDA. That methodology is completely broken for hybrid media assets.
If you value Curzon purely on its theater cash flows, you get a modest number dragged down by lease liabilities. If you value it as a vertically integrated UK distribution powerhouse with a captive retail storefront, the math changes entirely. Look at how MUBI has raised capital at massive tech-style valuations while aggressively moving into theatrical distribution and physical cinema spaces. The market is actively rewarding companies that bridge the gap between physical curation and digital streaming.
The lazy consensus assumes that private equity selling a cinema chain is a bearish signal for the big screen. In reality, it proves the exact opposite. The financial engineers did their job: they stripped out the existential bankruptcy risk, expanded the footprint during a generational downturn, and proved that affluent audiences will still pay £20 a ticket for a curated night out.
Now, Fortress is simply clearing the room so the media giants can bid on the keys.
How Media Operators Should Play This Shift
If you are running an independent distributor, a regional exhibitor, or a digital content platform, watching the Fortress-Curzon process from the sidelines without adjusting your own strategy is a mistake. The playbook is sitting right in front of you:
- Stop Selling Commodities: If your business relies on renting out dark rooms to play the exact same studio releases available at the multiplex down the street, your margins will compress to zero. Physical space only holds value if it offers an experience—curation, community, hospitality—that cannot be replicated on a 65-inch OLED television.
- Own the Downstream Rights: Exhibition without distribution is a low-margin real estate trap. Distribution without guaranteed exhibition leaves you begging gatekeepers for screen time. Even at a micro-level, exhibitors must partner directly with filmmakers and niche distributors to share in the digital backend of the audiences they build in the theater.
- Treat Venues as Media Channels, Not Real Estate: Stop measuring square footage solely by concession revenue per head. Measure it by brand equity, membership conversion, and data capture.
Fortress isn't running for the exits because the lights are going out on cinema. They are walking away because they know the difference between a distressed asset and a finished product—and they have no intention of paying retail price to stick around for the second act.