Market capitalization milestones function as psychological markers rather than fundamental economic signals. When Advanced Micro Devices brushes against the trillion-dollar valuation threshold while market commentators proclaim the expansionary run is far from over, analysts must deconstruct the underlying economic engines rather than reacting to index momentum. Achieving and sustaining a twelve-figure enterprise value in the semiconductor sector requires a structural shift in gross margin expansion, addressable market capture, and capital expenditure efficiency.
Evaluating this trajectory demands a framework that isolates cyclical hardware demand from structural compute dominance. The mechanics driving high-valuation semiconductor entities rest on three foundational variables: silicon yield economics, software ecosystem lock-in, and enterprise capital expenditure allocation cycles. If you liked this post, you should read: this related article.
The Architecture of Silicon Valuation and Capital Allocation
Semiconductors operate under intense fixed-cost burdens. Research, development, and advanced node foundry commitments demand billions of dollars before a single unit ships to an enterprise customer. Consequently, valuation expansion cannot rely solely on volume growth; it requires pricing power derived from performance differentiation.
When an enterprise or hyperscale cloud provider evaluates procurement options for artificial intelligence infrastructure or high-performance data center processing units, the decision function hinges on total cost of ownership rather than raw component cost. Total cost of ownership encompasses power consumption, rack-space density, compilation overhead, and latency profiles. For another look on this story, see the recent coverage from MIT Technology Review.
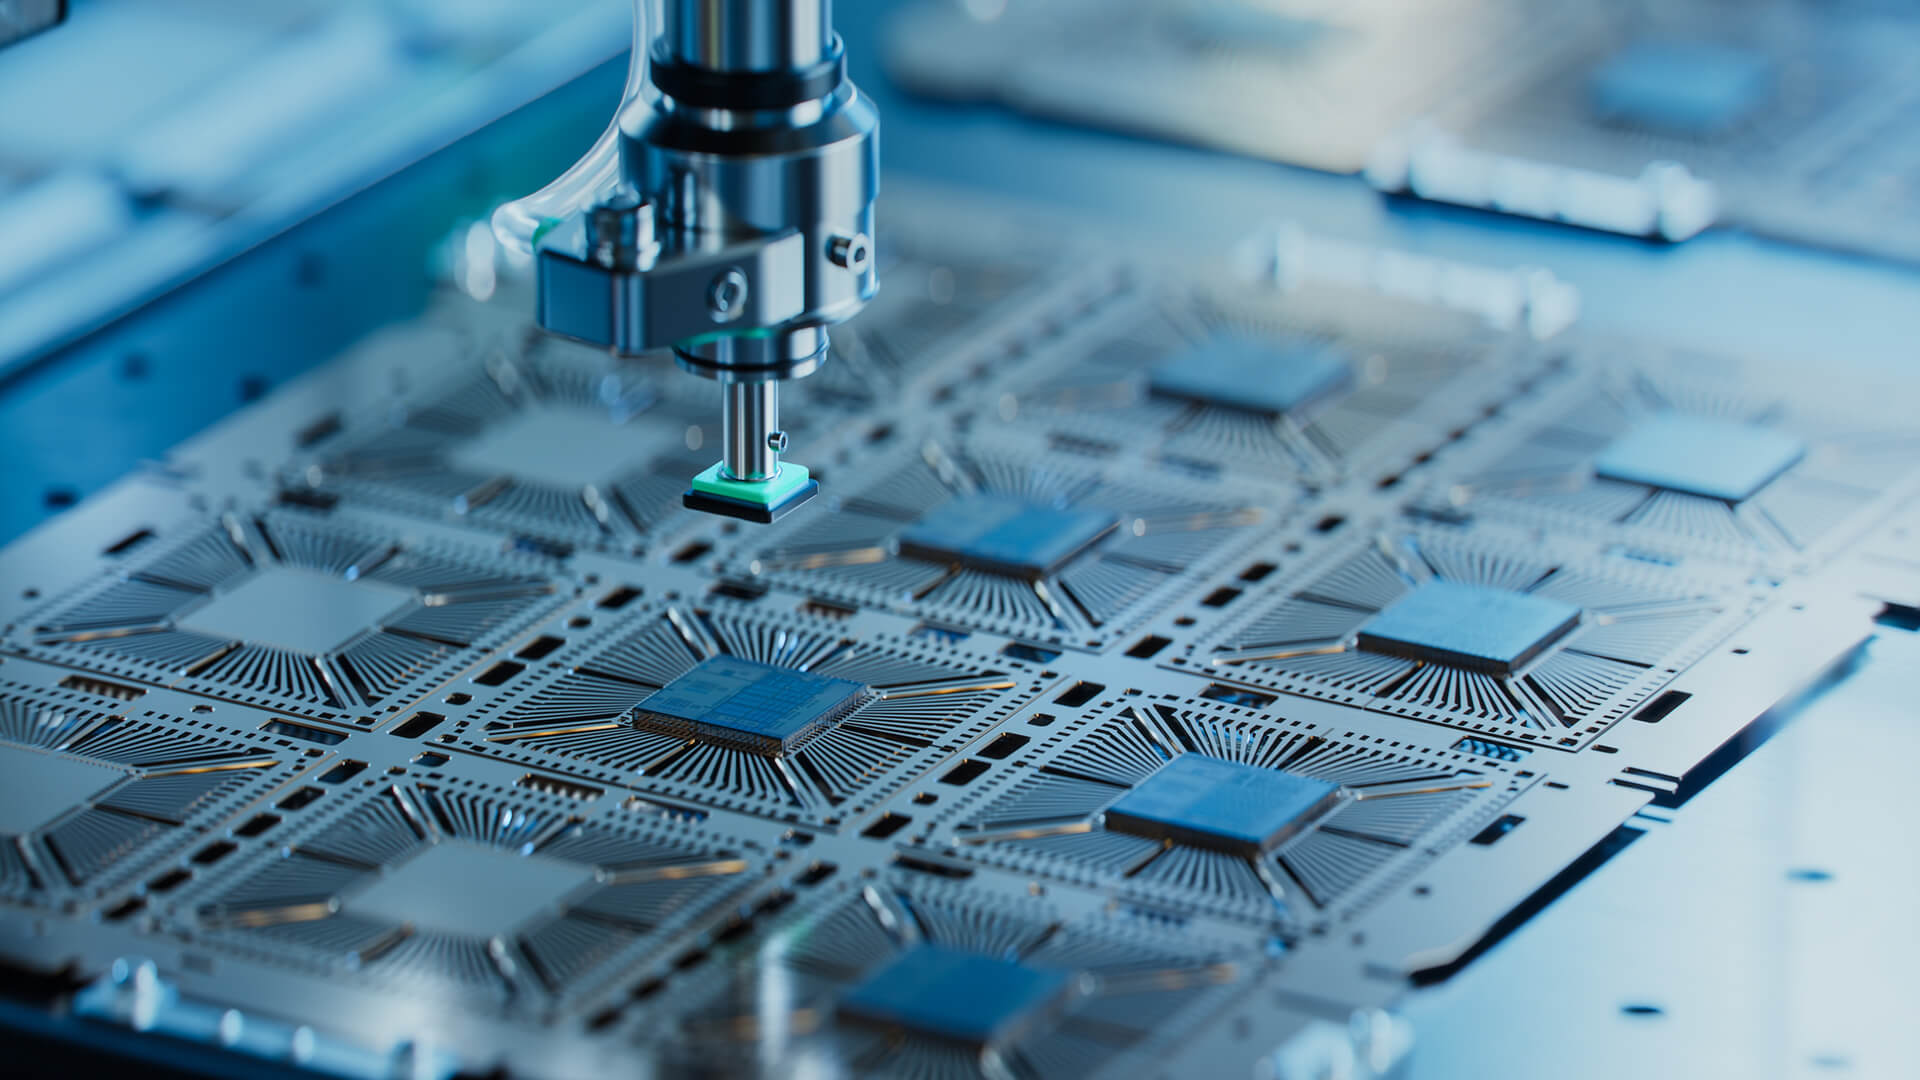
Advanced Micro Devices captures market share by exploiting the efficiency frontier of heterogeneous computing and modular design. By decoupling the input/output controller die from the core compute chiplets, manufacturing yields improve significantly on leading-edge foundry nodes. This structural architectural advantage alters the unit economics of production, protecting gross margins even when foundry wafer costs escalate.
However, hardware efficiency alone fails to secure long-term pricing power. The moat in modern compute valuation resides within the software stack. If an enterprise must expend excessive engineering hours recompiling or optimizing codebases to run efficiently on alternative silicon architectures, the switching friction remains high, neutralizing minor hardware price advantages.
The Hyperscale Demand Function and Capacity Bottlenecks
The market narrative surrounding continuous valuation expansion often treats enterprise artificial intelligence spending as an infinite linear trend. Rigorous analysis requires examining the actual demand function, which is governed by the capital expenditure budgets of major cloud service providers and sovereign compute initiatives.
Hyperscalers allocate capital based on projected return on invested capital from cloud services and proprietary models. This creates a cyclical feedback loop. When cloud providers accelerate infrastructure deployment, semiconductor suppliers experience rapid revenue acceleration. Yet, this demand is constrained by three hard physical limits:
- Advanced packaging capacity, specifically CoWoS or equivalent high-density integration lines.
- Data center power availability and thermal dissipation limits.
- Memory bandwidth bottlenecks, driven by high-bandwidth memory supply constraints.
Valuation models that project sustained parabolic growth must account for these supply-side ceilings. If the ecosystem cannot manufacture sufficient interposers or secure stable electrical grid allocations for new data center builds, revenue realization hits an absolute physical boundary, regardless of order book depth.
Margin Resilience Under Competitive Pressure
Market expansion attracts aggressive competitive responses. The incumbent market leader possesses deep financial reserves and entrenched customer relationships, while specialized application-specific integrated circuit initiatives from major technology conglomerates aim to internalize workloads entirely, bypassing merchant silicon providers altogether.
To maintain pricing discipline in this environment, a challenger must demonstrate architectural agility. The historical playbook of competing purely on price compression destroys the capital reserves necessary to fund the subsequent node generation. Sustainable margin expansion relies on generational performance-per-watt leadership and rapid product cadence.
When analyzing whether a multi-trillion-dollar ceiling is sustainable, market participants must separate top-line revenue velocity from free cash flow conversion. High-valuation regimes punish businesses that require escalating capital expenditures to generate incremental revenue dollars. The operational imperative is maintaining capital efficiency while scaling production to meet enterprise workloads.
Strategic Execution and Downside Vectors
The assumption that an extended market run will persist indefinitely ignores structural vulnerabilities. Enterprise technology spending is inherently volatile, subject to macroeconomic tightening, sudden shifts in model architecture efficiency that reduce training compute requirements, and geopolitical risks concentrated in East Asian semiconductor manufacturing hubs.
If model architectures evolve to require significantly fewer parameters or shift toward inference-heavy local execution, the demand mix for high-end training silicon will experience a structural composition shift. Inference workloads prioritize cost-per-query and power efficiency over raw cluster throughput, altering the competitive dynamics between merchant silicon suppliers and proprietary accelerators.
Strategic positioning within this sector requires tracking three distinct operational metrics: gross margin trajectory independent of packaging subsidies, software developer adoption rates outside of core hyperscale clients, and free cash flow yield relative to enterprise value.
Capital allocation strategies must focus on securing multi-year supply agreements with advanced foundries while aggressively expanding software compiler compatibility to lower the friction of enterprise migration. The path to sustained valuation dominance is secured not by market sentiment or media commentary, but by maintaining an unassailable advantage in performance per watt and total cost of ownership at scale.