The intersection of state executive clemency and judiciary punitive mechanics creates a distinct fiscal friction point. When a judicial apparatus imposes a mandatory financial penalty as a mandatory prerequisite for sentence mitigation or house arrest conversion, the case transitions from a purely criminal proceeding into an exercise in asset liquidity management. The core structural tension centers on a simple formula: an individual facing a high-value judicial penalty possesses finite liquid reserves, forcing an external institutional dependency to clear the liability.
The Mechanics of Conditional Clemency
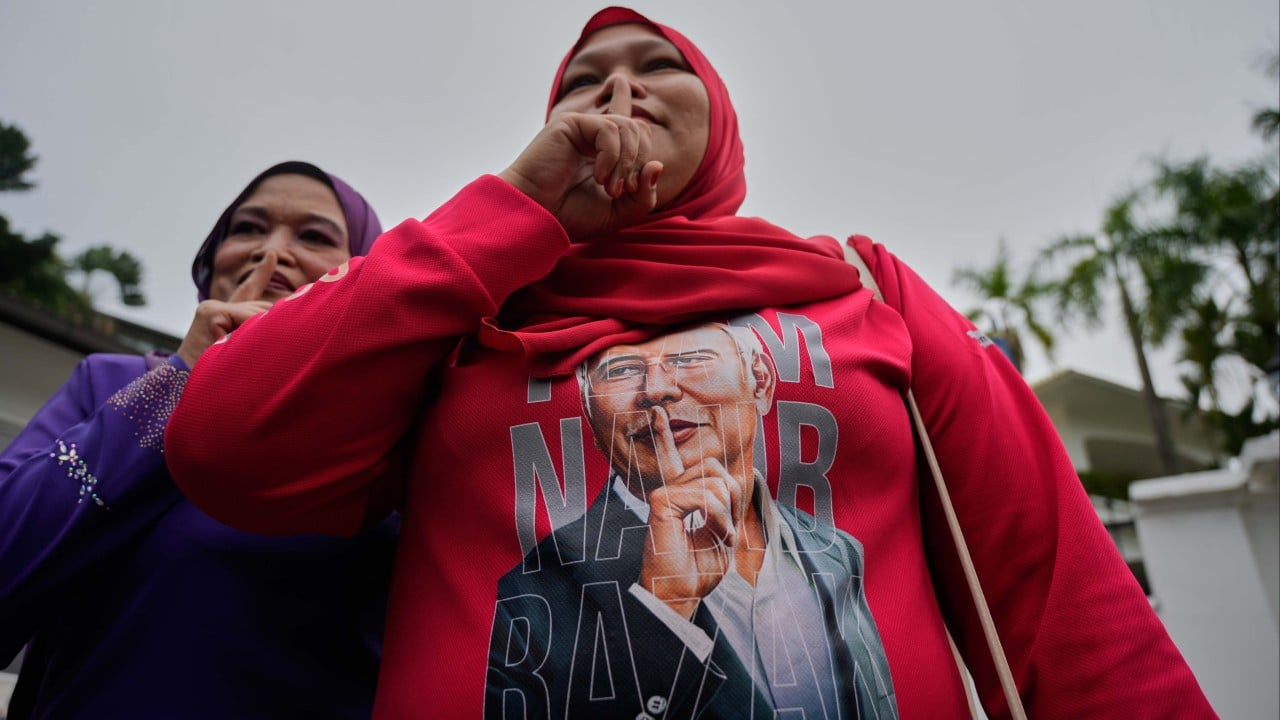
Judicial penalties tied to white-collar convictions function as state-enforced balance sheet impairments. In the matter involving former Malaysian Prime Minister Najib Razak, the reduction of a 210 million ringgit penalty down to 50 million ringgit via executive pardons board intervention established a specific financial threshold for custodial relocation. You might also find this connected article insightful: La production de missiles Patriot en Ukraine est une illusion industrielle.
The primary structural bottleneck in such legal frameworks is the separation of powers between executive clemency and judicial debt collection. While an executive authority may grant conditional commutation permitting home detention, the judiciary's administrative arm requires absolute settlement of outstanding monetary orders before executing the release mechanism. This creates a binary compliance state:
- Capital Deficiency: The subject holds substantial asset wealth tied up in contested receiverships, frozen accounts, or civil forfeiture litigation, resulting in immediate insolvency for cash transactions.
- Transactional Friction: The mechanics of paying a multi-million-dollar penalty require physical or electronic high-value clearing channels, such as cashier checks or direct court registry deposits, which expose the source of funds to regulatory tracking and anti-money laundering compliance audits.
The Cost Function of Political Patronage
When a primary debtor faces capital insolvency, the burden of liability shifts to political or organizational proxies. In political economies, entities such as dominant ruling parties or allied factions function as lender-of-last-resort networks. As discussed in recent coverage by USA Today, the results are notable.
The political cost function operates through two distinct channels:
- Direct Fundraising Crowdsourcing: Public or semi-public donation drives establish decentralized capital accumulation, though these methods suffer from high public friction and limited yield velocities. For example, solidarity funds established to offset legal debts frequently capture only a fraction of the total liability within compressed operational windows, highlighting a severe liquidity mismatch between grassroots mobilization and high-value court requirements.
- Institutional Bailouts: When grassroots mechanisms fail to clear the deficit, central party treasuries or institutional benefactors must intervene. This introduces systemic moral hazard and alters internal party dynamics, as deploying massive liquid reserves for an individual legal liability depletes operational capital reserved for electoral cycles and institutional maintenance.
Asset Architecture and Legal Constraints
The inability to pay a court-ordered fine despite high-profile status illustrates the efficacy of modern asset-tracking regimes. Modern financial investigation units systematically sever access to legacy wealth through interconnected instruments:
- Civil Recovery Suits: Parallel actions by state-linked entities freeze specific asset classes, preventing the liquidation of real estate or corporate equity to satisfy criminal penalties.
- Account Sequestration: Direct freezing orders on personal and corporate accounts eliminate primary liquidity sources, forcing defendants into a state of structural bankruptcy regarding unencumbered cash.
The resolution of such high-stakes financial impasses ultimately requires institutional syndication. When the primary beneficiary cannot meet the statutory cost of freedom, the liability is absorbed by external political stakeholders who calculate that the utility of the individual's release outweighs the opportunity cost of depleting organizational liquidity reserves. The transaction clears not through individual solvency, but through collective political capitalization.