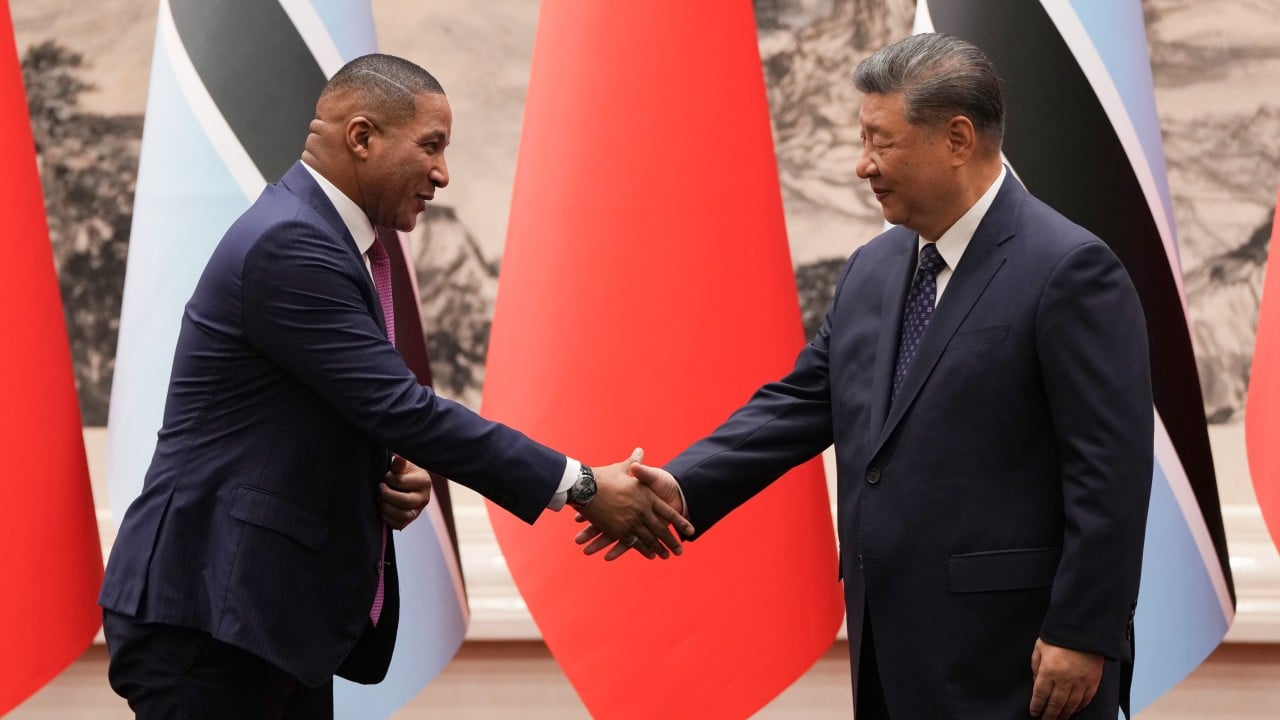
When Beijing declares that African mineral wealth belongs to Africa and warns against geopolitical rivalry, the statement operates as a strategic positioning move inside a supply chain battle where refining capacity, not raw ore, dictates market power. Surface-level coverage treats this clash as a contest of slogans—Washington chasing mining concessions against Beijing preaching sovereignty and local industrialization. That framing misses the structural economics of mineral extraction. African nations hold roughly 30% of the world's critical mineral reserves, yet owning subterranean deposits does not automatically translate into high-margin industrial capture.
Deconstructing the Competitor Narrative
Standard reporting on Sino-American mineral competition in Africa follows a predictable script. It pairs a diplomatic soundbite from Xi Jinping about sovereignty and mutual benefit with a list of Western counter-moves, such as bilateral mining access initiatives or supply chain agreements. The implicit logic runs like this: two superpowers want cobalt, copper, lithium, nickel, and rare earths; one warns against rivalry while offering industrialization; therefore, African states face a binary choice between competing patrons.
Three analytical flaws weaken that framing. First, it treats diplomatic rhetoric as a substitute for contract mechanics. Sovereign declarations do not override offtake agreements, equity structures, or project finance terms that govern where ore goes and who captures downstream margins. Second, it conflates mine ownership with midstream and downstream control. In global mineral supply chains, concentration bottlenecks often sit in smelting, chemical refining, magnet manufacturing, and battery precursor production rather than raw extraction alone. Third, it assumes geopolitical competition automatically transfers bargaining power to host governments. Competing bidders can raise headline offers, yet capital-intensive greenfield projects carry long lead times, permitting risk, and infrastructure deficits that constrain how aggressively host states can push terms without stalling investment.
The Four-Layer Mineral Value Chain
To evaluate any diplomatic warning or mining deal rigorously, separate the mineral sector into four distinct operational layers:
- Upstream Extraction: Geological exploration, permitting, mine construction, and ore or concentrate production. Lead times often span years or more than a decade, and capital intensity is high.
- Midstream Beneficiation and Refining: Crushing, concentration, smelting, and chemical conversion into battery-grade salts, metals, or alloys. This stage frequently exhibits sharper geographic concentration and tighter technical moats than mining itself.
- Component Manufacturing: Turning refined inputs into cathodes, anodes, sintered magnets, specialty alloys, or precursor chemicals tailored to industrial specifications.
- End-Use Integration: Embedding components into electric vehicles, grid storage, defense systems, electronics, and data center hardware.
A country can export millions of tonnes of raw ore or concentrate while capturing only a thin slice of total value added if midstream refining and component fabrication occur elsewhere. Conversely, a state or firm that controls refining and processing can shape pricing, bottlenecks, and trade flows even when raw ore originates across multiple jurisdictions.
Why "No Rivalry" Rhetoric Is Strategic Leverage
Rhetoric opposing geopolitical rivalry serves concrete commercial and diplomatic functions for Beijing. First, it frames Chinese financing, infrastructure, and processing investments as alignment with African industrial aspirations rather than extractive competition. Because many African governments prioritize domestic beneficiation, job creation, and export diversification—and several have enacted export restrictions or policies pushing for local processing—framing engagement around value addition speaks directly to host-country policy goals.
Second, anti-rivalry messaging pushes back against efforts by the United States and partner economies to diversify supply chains away from concentrated nodes. When Washington pursues preferential access to designated assets or builds alternative sourcing coalitions, Beijing's counter-narrative portrays rival blocs as politicizing trade while positioning itself as a long-standing development partner.
A crucial distinction separates known facts from educated hypotheses here. It is a documented pattern that Chinese state and commercial actors have built deep positions across mining, refining, and industrial supply chains, and that Xi has explicitly linked African mineral cooperation to industrial added value while warning against geopolitical rivalry. It is an educated hypothesis—not a certainty—that rhetorical emphasis on sovereignty and local processing will permanently insulate Chinese-linked supply chains from Western competition or automatically shift high-value manufacturing onto African soil.
Cause-and-Effect Dynamics Standard Coverage Misses
Several causal chains shape how this rivalry plays out on the ground, yet receive little attention in headline summaries:
- Financing-to-Offtake Lock-In: Project debt, concessional loans, or upfront infrastructure packages frequently tie future output to specific buyers or processing routes. Even when formal title remains sovereign, commercial lock-in can limit a government's ability to redirect supply or shop for better downstream terms later.
- Refining Bottlenecks vs. Deposit Abundance: Having reserves in the ground does not create immediate refining capacity. Smelters and chemical plants require reliable baseload power, specialized industrial chemistry, environmental compliance, and skilled operators. Building alternative mining and refining capacity in North America or elsewhere faces multi-year construction timelines and political or regulatory friction, which keeps incumbent processing hubs influential in the near term.
- Export Bans Without Domestic Bottleneck Removal: When producer countries restrict raw mineral exports to force local processing, the policy creates a test of industrial readiness. If power supply, transport corridors, capital access, and technical skills lag behind, export curbs risk slowing project cash flows or triggering disputes rather than immediately spawning competitive domestic refineries.
- Local Processing vs. Deep Industrialization: Building a smelter or basic processing plant increases domestic activity compared to shipping raw ore, yet basic processing is not the same as deep technology transfer, high-skilled engineering employment, or broad manufacturing spillovers. Without binding contractual terms and domestic supplier participation, value capture can remain narrow.
Operational Reality for Host Governments and Investors
Consider a hypothetical copper or lithium concession in a mineral-rich jurisdiction. A foreign consortium offers rapid mine development plus a local concentration or smelting facility, while a rival bidder from another bloc offers technical assistance and alternative export routes. If the host government signs a deal focused only on headline investment volume or tax rates without enforceable commitments on local procurement, workforce training, grid integration, and environmental safeguards, the project can still leave domestic industrial capacity shallow.
At the same time, over-indexing on ideological alignment with either Washington or Beijing carries operational risk. Western initiatives often face budget cycles, legislative scrutiny, and longer project timelines, whereas deep integration into a single dominant processing ecosystem can tie a producer's pricing and logistics to that ecosystem's industrial priorities. Host policymakers who treat foreign capital as a set of separable commercial and technical packages—rather than an all-or-nothing geopolitical allegiance—preserve wider room to maneuver.
Limits of the Strategy and Strategic Play
No negotiating framework eliminates structural trade-offs. Capital-scarce states face a real tension between demanding tough local-content or beneficiation rules and keeping project returns bankable enough to attract patient capital. Overly rigid mandates can delay bankable financing, while overly permissive concessions surrender long-term value. Furthermore, framework agreements and policy declarations frequently lack independent verification or strong community grievance mechanisms, meaning implementation quality varies sharply from mine to mine.
The sharpest strategic play for an African mineral producer—or an industrial buyer advising one—is to unbundle concessions by value-chain stage and tie incentives to verified midstream milestones. Instead of granting sweeping multi-stage rights under a single package or relying on non-binding pledges of "value addition," structure agreements around staged performance: tie fiscal incentives, infrastructure co-investment, or export privileges to concrete milestones in local beneficiation, power reliability, technical training, and audited environmental compliance. Competition between rival powers only works in a producer's favor when host institutions convert geopolitical attention into enforceable, stage-gated industrial contracts.